
What Types of Wealth Management Expertise Should You Look for in a Melbourne Financial Adviser?
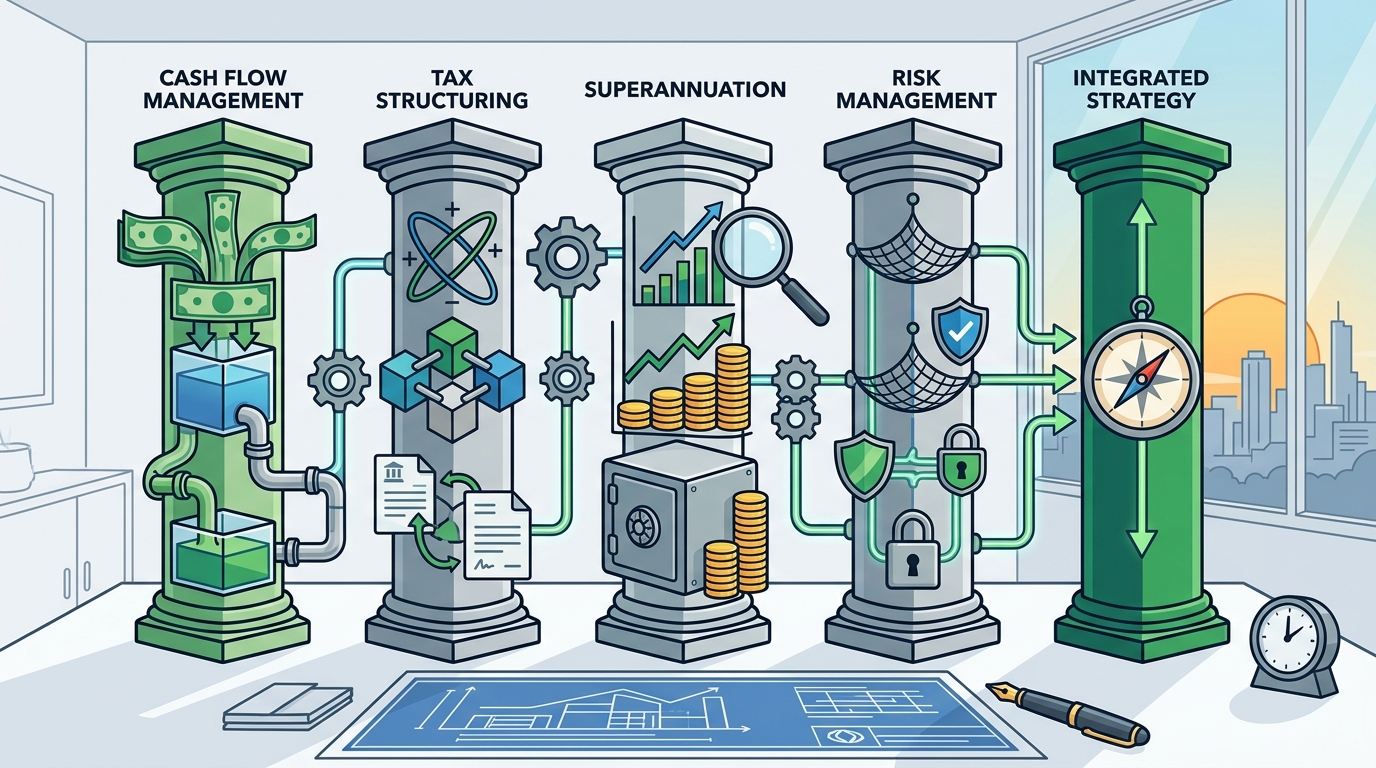
When selecting a Melbourne financial adviser, you should look for integrated expertise across cash flow, tax structuring, superannuation, and risk management. A strong adviser connects these areas into a single strategy rather than treating them as isolated products. This holistic approach ensures your financial decisions support your long-term goals and lifestyle ambitions.
The Importance of Integrated Strategy
Many individuals hold investments, insurance, and superannuation accounts that operate in silos. This fragmentation often leads to missed opportunities and inefficient tax outcomes. An integrated strategy is a coordinated plan that aligns all financial components toward a unified objective. For example, a professional in Melbourne might need to balance salary sacrifice contributions with mortgage repayments to optimize after-tax cash flow. Without a unified view, these decisions can conflict, reducing overall wealth accumulation. At Obsidian Wealth, we emphasize that wealth is built through structure and consistent action, not just high income.
Tax Minimisation and Structuring
Tax is often the largest drag on wealth creation for high-income earners. Tax minimisation is the process of legally reducing your tax liability through appropriate structuring of income and assets. In Australia, the tax system offers various concessions for superannuation contributions and investment structures. A skilled adviser will work with your accountant to ensure your ownership structures, such as trusts or companies, align with your financial goals. For instance, understanding the difference between concessional and non-concessional superannuation caps is critical for maximizing tax efficiency. This expertise ensures that your financial decisions are made with an after-tax perspective, rather than relying on headline returns.
Superannuation and Retirement Planning
Superannuation is a cornerstone of retirement security in Australia, yet it involves complex rules and choices. Superannuation planning is the strategic management of contributions, investment settings, and retirement income options. Recent changes, such as the introduction of Division 296 tax on large balances, require up-to-date knowledge to avoid unnecessary costs. An adviser should help you determine the optimal balance between growth and defensive assets based on your age and retirement timeline. They should also guide you on transition to retirement strategies, which allow you to draw down super while still working. This expertise is vital for ensuring your retirement income is sustainable and tax-efficient.
Risk Management and Insurance
Building wealth without protection is like building a house on sand. Risk management is the process of identifying and mitigating financial threats such as illness, injury, or death. Insurance is a critical component of this, but it must be tailored to your specific circumstances. A competent adviser will review your existing cover for life, total and permanent disability, and income protection. They will identify gaps and ensure your premiums are affordable relative to your income. For example, a business owner needs different protection than a salaried professional. This layer of security ensures that a single adverse event does not derail your long-term financial plan.
Investment Guidance and Portfolio Structuring
Investment advice should be grounded in a clear understanding of your goals and risk tolerance. Portfolio structuring is the process of allocating assets across different classes, regions, and managers to achieve diversification. A good adviser will consider the costs, tax implications, and liquidity needs of each investment. They will help you decide whether assets should be held personally, jointly, or through a trust. This approach ensures that your portfolio is not just diversified but also aligned with your broader financial strategy. At Obsidian Wealth, we focus on building investment approaches with a clear purpose, considering diversification, costs, tax, and risk alongside when you may need to use the money.
Key Takeaways
- Look for an adviser who integrates cash flow, tax, super, and insurance into a single plan.
- Tax structuring expertise is essential for high-income earners to minimize liability.
- Superannuation planning must account for current rules, including Division 296.
- Risk management ensures that your wealth is protected against life's uncertainties.
- Investment advice should be tailored to your specific goals and risk tolerance.
- Choose an adviser who collaborates with your accountant and lawyer for a holistic view.
Frequently Asked Questions
What is the difference between a financial planner and a wealth manager?
A financial planner typically focuses on creating a comprehensive plan for your financial life, while a wealth manager often manages the assets themselves. In practice, many advisers in Melbourne offer both services, providing advice and managing investments under one roof.
How important is tax advice in wealth management?
Tax advice is critical because it directly impacts your after-tax returns. A good adviser will coordinate with your accountant to ensure your financial structures are tax-efficient, helping you retain more of your wealth.
Should I use a fee-for-service adviser?
Fee-for-service advisers are paid directly by you for their advice, rather than receiving commissions from product providers. This model can reduce conflicts of interest, as the adviser is incentivized to provide the best advice for your situation, not to sell a specific product.
What role does insurance play in wealth management?
Insurance acts as a safety net, protecting your income and assets from unexpected events. Without adequate cover, a single incident like illness or injury could force you to liquidate investments or derail your retirement plans.
How often should I review my financial plan?
You should review your financial plan at least annually or whenever there is a significant change in your life, such as a job change, marriage, or inheritance. Regular reviews ensure your plan remains aligned with your goals and current circumstances.
Can an adviser help with estate planning?
While advisers do not provide legal advice, they can coordinate with your lawyer to ensure your financial arrangements align with your estate planning wishes. This collaboration helps ensure your wealth is passed on to the people you intend to benefit.
Choosing the Right Partner for Your Wealth
Selecting the right financial adviser in Melbourne requires looking beyond product recommendations to the depth of their strategic expertise. You need a partner who can integrate your cash flow, tax position, superannuation, and risk management into a cohesive plan. At Obsidian Wealth, we provide private wealth advice for professionals, business owners, families, and retirees, helping you make financial decisions with a clear view of your position and the choices ahead. We work with your accountant and lawyer to ensure all aspects of your financial life are aligned. To discuss how we can help you build a tailored wealth plan, book a free 15-minute call with our team.