
Choosing the Right Financial Adviser in Melbourne for Wealth Creation
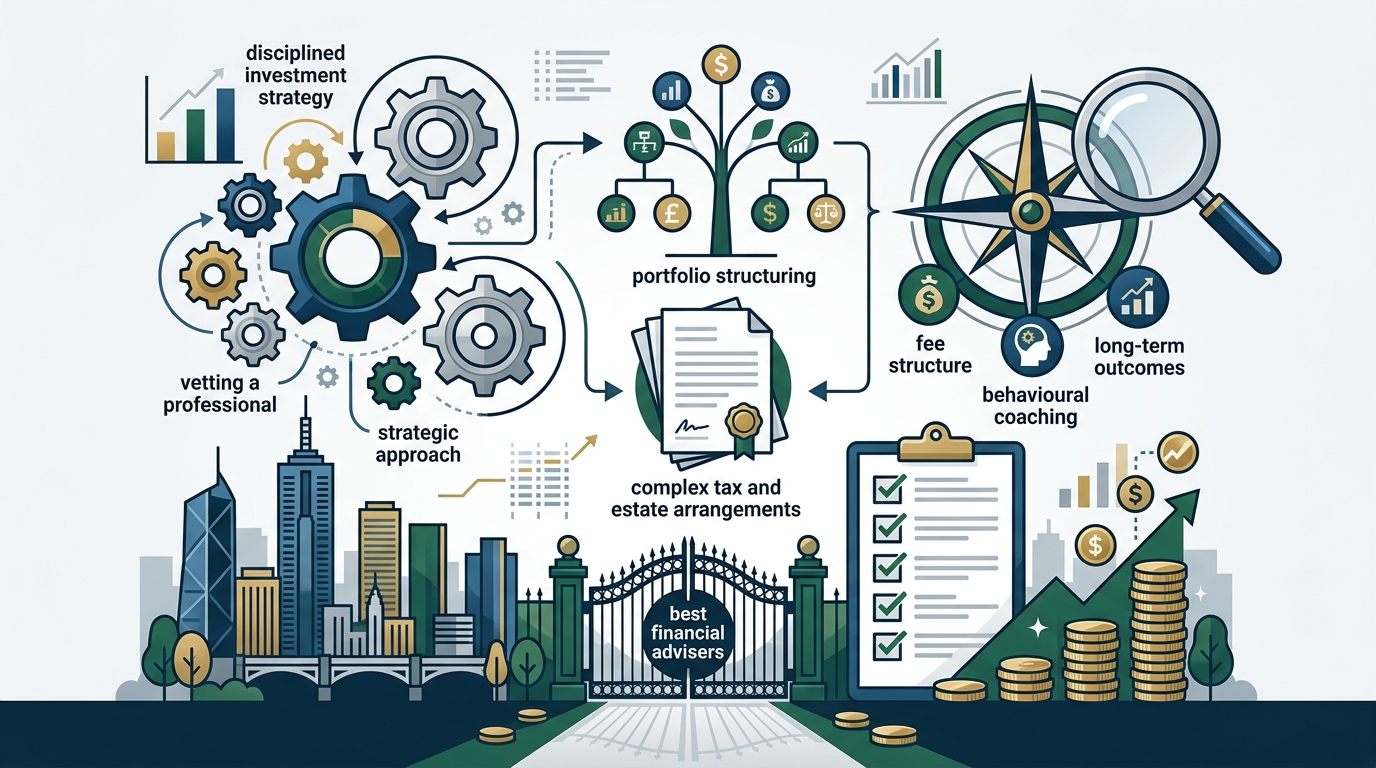
Choosing the right financial adviser in Melbourne for wealth creation requires evaluating an adviser's strategic approach, fee structure, and ability to coordinate complex tax and estate arrangements. This guide outlines the essential criteria for selecting a private wealth adviser, detailing how disciplined portfolio structuring and behavioural coaching drive long-term outcomes. It covers the specific strategies used to build wealth and the practical steps for vetting a professional in the Australian market.
The Landscape of Melbourne Financial Advisers
Melbourne is a major hub for financial services in Australia, offering a wide range of advisory firms. A financial adviser is a licensed professional who provides advice on financial products and services, including investments, superannuation, and insurance. The market is generally divided into two primary models: fee-only advisers and commission-based advisers. Fee-only advisers are paid directly by the client, which aligns their interests with the client's long-term financial health. Commission-based advisers may receive payments from product providers, which can sometimes create conflicts of interest.
Fee-Only vs. Commission-Based Models
When evaluating advisers, the payment model is a critical first step. Fee-only firms, such as Obsidian Wealth, typically charge a fixed fee or a percentage of assets under advice. This model ensures that the adviser's income is not tied to selling specific products. In contrast, commission-based models may incentivize the purchase of certain funds or insurance policies. For high-net-worth individuals and business owners, the fee-only model is often preferred because it prioritizes the overall structure of the portfolio rather than individual product sales.
The Role of Private Wealth Practices
Private wealth practices focus on clients with more complex financial situations, such as business owners, professionals, and retirees. These firms often provide a holistic view of finances, integrating cash flow, debt, investments, and estate planning. A private wealth adviser is a specialist who manages the financial affairs of high-net-worth individuals, focusing on the preservation and growth of assets. In Melbourne, many firms operate from Level 14, 333 Collins Street, a central location that reflects the city's status as a financial center. The choice of adviser should reflect the complexity of your financial life, not just the size of your portfolio.
Core Wealth Creation Strategies
Wealth creation is not a single action but a series of coordinated decisions. Wealth creation strategy is the systematic process of increasing net worth through disciplined saving, investing, and tax optimization. The most effective strategies focus on the compounding effect of time and the reduction of friction, such as high fees and poor asset allocation. Understanding these core components helps clients evaluate whether an adviser's approach is grounded in evidence-based practice.
Asset Allocation and Diversification
Asset allocation is the division of an investment portfolio among different asset categories, such as shares, fixed income, and property. Diversification is the practice of spreading investments across various asset classes to reduce risk. Research consistently shows that asset allocation is the primary driver of long-term portfolio returns, far more so than the selection of individual stocks or funds. A disciplined approach involves rebalancing the portfolio periodically to maintain the target risk level. This prevents the portfolio from becoming too aggressive or too defensive over time.
Tax-Efficient Structuring
Tax is a significant cost that can erode wealth if not managed carefully. Tax-efficient structuring is the arrangement of financial assets in a way that minimizes the tax liability on income, gains, and distributions. In Australia, this often involves the strategic use of superannuation, which offers tax advantages for contributions and earnings. Advisers work with accountants to ensure that ownership structures, such as trusts or companies, are aligned with the client's goals. The goal is not to avoid tax illegally, but to use the legal framework to retain more of the wealth generated.
Behavioural Coaching and Discipline
One of the most overlooked aspects of wealth creation is the client's behaviour. Behavioural coaching is the process of helping investors make rational decisions during periods of market volatility. Studies suggest that the single largest component of an adviser's measurable value is stopping clients from making emotional mistakes, such as selling in a panic or chasing hot assets. A good adviser provides a steady hand, ensuring that the long-term plan is not abandoned due to short-term market noise. This discipline is often more valuable than the specific investments chosen.
Essential Adviser Selection Criteria
Selecting a financial adviser is a significant decision that requires due diligence. Adviser selection criteria are the specific standards and questions used to evaluate a professional's suitability for your financial needs. These criteria go beyond marketing materials and focus on the adviser's process, qualifications, and alignment with your goals. A systematic approach to selection helps ensure that the relationship is built on trust and competence.
Qualifications and Licensing
All financial advisers in Australia must be licensed under the Corporations Act 2001. A licensed financial adviser is a professional who has met the regulatory requirements to provide financial advice, including holding an Australian Financial Services Licence (AFSL) or being an Authorised Representative of a licensee. It is important to verify the adviser's license number and check for any disciplinary history. Additionally, look for professional qualifications such as the Chartered Financial Analyst (CFA) or the Certified Financial Planner (CFP) designation, which indicate a higher level of expertise and ethical commitment.
Scope of Services and Coordination
Not all advisers offer the same range of services. Some focus solely on investments, while others provide comprehensive planning that includes estate, tax, and insurance advice. A comprehensive financial adviser is a professional who provides advice across multiple areas of a client's financial life, ensuring that all components work together. It is important to ask how the adviser coordinates with other professionals, such as accountants and lawyers. A strong adviser will facilitate these conversations to ensure that the overall plan is coherent and that there are no gaps in coverage.
Fee Structure and Transparency
Understanding how an adviser is paid is crucial for avoiding conflicts of interest. A transparent fee structure is a clear and detailed explanation of all costs associated with financial advice, including management fees, platform fees, and transaction costs. Ask for a breakdown of all fees and how they are calculated. Some advisers charge a fixed fee for advice, while others charge a percentage of assets under management. It is also important to understand if there are any performance fees or hidden costs. Transparency in fees is a strong indicator of an adviser's integrity and commitment to the client's best interests.
| Criteria | What to Look For | Why It Matters |
|---|---|---|
| Payment Model | Fee-only vs. Commission-based | Aligns adviser incentives with client goals |
| Qualifications | AFSL, CFA, CFP designations | Ensures regulatory compliance and expertise |
| Service Scope | Holistic planning vs. Single-product focus | Ensures all financial areas are coordinated |
| Fee Transparency | Clear breakdown of all costs | Prevents hidden costs and conflicts of interest |
| Behavioural Support | Coaching during market volatility | Prevents emotional decision-making |
Key Takeaways
- Fee-only advisers are often preferred for wealth creation as they avoid conflicts of interest associated with commissions.
- Asset allocation is the primary driver of long-term returns, not stock picking.
- Tax-efficient structuring, particularly through superannuation, is a critical component of wealth growth.
- Behavioural coaching helps prevent costly emotional mistakes during market downturns.
- Verify an adviser's license and professional qualifications before engaging their services.
- Ensure the adviser coordinates with your accountant and lawyer for a holistic plan.
- Request a clear breakdown of all fees to ensure transparency and alignment of interests.
Frequently Asked Questions
What is the difference between a financial planner and a financial adviser?
In Australia, the terms are often used interchangeably, but a financial adviser is the licensed professional who provides advice on financial products. A financial planner may focus more on the overall strategy and may not always be licensed to provide product-specific advice. For wealth creation, you need a licensed financial adviser who can implement the strategy.
How much does a financial adviser cost in Melbourne?
Costs vary widely. Fee-only advisers may charge a fixed fee for advice or a percentage of assets under management, typically between 0.5% and 1.5% per year. Commission-based advisers may charge less upfront but earn commissions from product providers. It is important to understand the total cost of advice, including platform and management fees.
Do I need a financial adviser if I have a good accountant?
An accountant focuses on tax compliance and reporting, while a financial adviser focuses on investment strategy and wealth growth. They serve different purposes and work best when coordinated. A financial adviser can help you make investment decisions that are tax-efficient, working alongside your accountant to ensure the overall plan is optimized.
How often should I review my financial plan?
It is recommended to review your financial plan at least once a year, or after any significant life event such as a change in income, marriage, or retirement. Regular reviews ensure that the plan remains aligned with your goals and that any changes in the market or your circumstances are addressed.
What is the role of superannuation in wealth creation?
Superannuation is a tax-advantaged retirement savings system. Contributions and earnings in super are taxed at a lower rate than personal income. For many Australians, super is the largest component of their wealth. An adviser can help you maximize contributions and choose the right investment options within your super fund.
How do I know if an adviser is acting in my best interest?
Look for a fee-only model, transparent fees, and a clear explanation of how the adviser is paid. A best-interest adviser will explain the costs and risks of their recommendations and will not push products that are not suitable for your situation. They should also be willing to work with your other professionals to ensure a holistic plan.
Final Thoughts
Selecting the right financial adviser is a critical step in the wealth creation process. By focusing on fee-only models, evidence-based strategies, and transparent fee structures, you can find a professional who is aligned with your long-term goals. Obsidian Wealth provides private wealth advice in Melbourne, helping professionals and business owners build wealth through disciplined investment strategy and long-term portfolio growth. To plan your visit, for a free 15-minute introductory call.