
Choosing an independent wealth adviser in Melbourne often provides a broader, more objective perspective on your financial life compared to big bank advisors. Independent firms are not tied to a single institution's products, allowing them to evaluate options across the entire market. This structural difference can lead to more tailored strategies for professionals and business owners who need holistic planning rather than just a single product recommendation.
Structural Differences in Advice
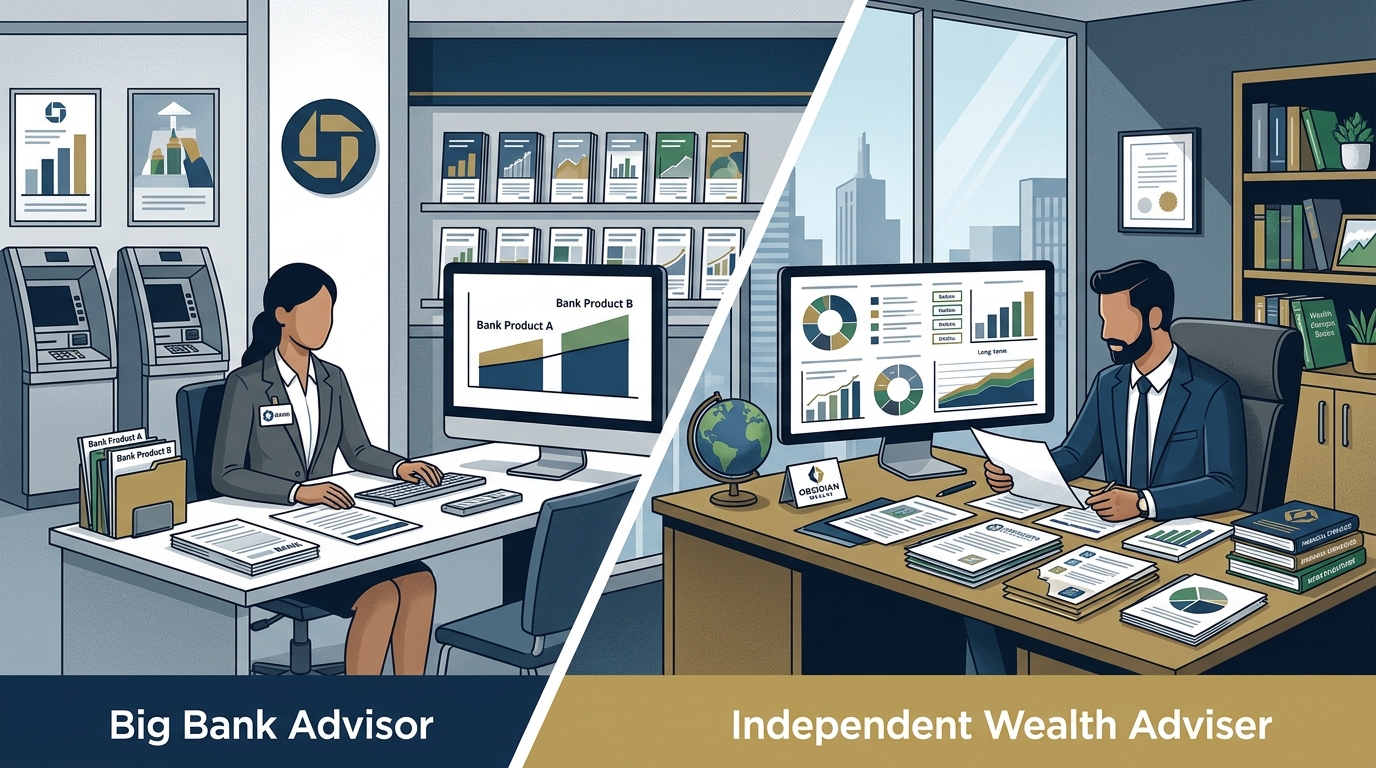
The primary distinction between an independent adviser and a big bank advisor lies in their employment and product access. A big bank advisor is typically an employee of a specific financial institution. Their role is often focused on selling that bank's proprietary products, such as their specific superannuation funds, insurance policies, or investment platforms. This creates a structural incentive to recommend products that generate revenue for the bank.
In contrast, an independent wealth adviser is not tied to a single institution. They have access to a wide range of products from various providers across the market. This independence allows them to select the most suitable option for your specific circumstances, rather than the option that is most profitable for their employer. For a Melbourne professional with a complex financial situation, this breadth of access is a significant advantage.
Implications for Objectivity
Because independent advisers are not restricted to one brand, they can provide a more objective assessment of your financial position. They can compare products from different providers to find the best fit for your goals, risk tolerance, and time horizon. This objectivity is crucial when making long-term financial decisions that will impact your retirement and wealth accumulation.
Product Availability and Conflict of Interest
Conflict of interest is a critical factor to consider when choosing financial advice. Big bank advisors may face conflicts when their personal compensation is tied to the sale of specific products. For example, they might receive higher commissions for selling a particular insurance policy or investment fund, which could influence their recommendation. This is a common concern in the financial industry and is why regulatory bodies emphasize the importance of disclosure.
Independent advisers, while also compensated for their services, are generally paid for the advice they provide rather than for selling specific products. This fee-for-service model can reduce the potential for conflict of interest. At Obsidian Wealth, our approach is grounded in providing advice that aligns with your best interests. We explain our fees and how we are paid clearly, ensuring transparency in our relationship with you.
Regulatory Framework
Both independent and big bank advisors are regulated by the Australian Securities and Investments Commission (ASIC). However, the nature of their compensation and product access can still lead to different outcomes. It is essential to ask your advisor about their compensation structure and any potential conflicts of interest before engaging their services.
Holistic Planning for Complex Needs
Big bank advisors often focus on specific products or services, such as mortgages or superannuation. While they may provide good advice within their area of expertise, they may not offer a comprehensive view of your entire financial life. Independent wealth advisers, on the other hand, are trained to provide holistic financial planning. This means they consider all aspects of your finances, including cash flow, debt, investments, insurance, tax, and estate planning.
For business owners and high-income professionals in Melbourne, this holistic approach is particularly valuable. Your financial situation is likely to be complex, involving multiple income streams, business structures, and investment portfolios. An independent adviser can bring all these elements together into a single, coherent plan. This ensures that your financial decisions are aligned with your overall life goals and that no critical area is overlooked.
Example: Business Owner Scenario
Consider a business owner who is considering selling their company. A big bank advisor might focus on the mortgage or superannuation aspects of the sale. An independent wealth adviser, however, would consider the tax implications, the diversification of the proceeds, the impact on their retirement income, and the estate planning needs. This comprehensive view helps ensure that the sale is structured in a way that maximizes the owner's long-term financial well-being.
Understanding Fee Structures
Fee structures are another key difference between independent and big bank advisors. Big bank advisors may offer some services for free, but this is often offset by higher product fees or commissions. Independent advisers typically charge a fee for their advice, which can be a fixed amount or a percentage of assets under management. While this may seem more expensive upfront, it can be more cost-effective in the long run if the advice leads to better investment outcomes and lower product fees.
It is important to understand how your advisor is paid before engaging their services. At Obsidian Wealth, we explain our fee structure clearly and agree on the scope and fees before any advice work proceeds. This transparency helps ensure that you are making an informed decision about the value you are receiving.
Comparing Costs
When comparing costs, it is essential to look at the total cost of ownership, including advice fees, product fees, and any other charges. A free advice service may come with higher product fees, which can erode your returns over time. An independent adviser who charges a fee for advice but recommends lower-cost products may ultimately be more cost-effective.
Key Takeaways
- Independent advisers have access to a wider range of products from various providers.
- Big bank advisors are tied to their employer's products, which can create conflicts of interest.
- Independent advisers provide holistic financial planning, considering all aspects of your financial life.
- Fee structures differ, with independent advisers typically charging for advice rather than selling products.
- Transparency in fees and conflicts of interest is crucial when choosing an advisor.
- For complex financial situations, such as business ownership, independent advisers can provide a more comprehensive view.
- Always ask your advisor about their compensation structure and how they are paid.
Frequently Asked Questions
Are independent advisers more expensive than big bank advisors?
Not necessarily. While independent advisers charge a fee for their advice, they may recommend lower-cost products, which can offset the advice fee. It is important to compare the total cost of ownership, including product fees.
Do big bank advisors provide good advice?
Big bank advisors can provide good advice within their area of expertise. However, their access to products is limited to their employer's offerings, which may not always be the best fit for your specific circumstances.
How do I know if an independent adviser is right for me?
Consider your financial situation and goals. If you have a complex financial life, such as business ownership or multiple income streams, an independent adviser may be a better fit. It is also important to feel comfortable with your advisor and confident in their ability to provide objective advice.
What is the difference between a fee-for-service and a commission-based advisor?
A fee-for-service advisor charges a fee for their advice, while a commission-based advisor is paid a commission for selling specific products. Fee-for-service advisors are generally considered to have fewer conflicts of interest.
Can I switch from a big bank advisor to an independent adviser?
Yes, you can switch advisors at any time. It is important to communicate your decision to your current advisor and ensure that your financial arrangements are transferred smoothly.
How do I find a qualified independent adviser in Melbourne?
Look for advisers who are registered with ASIC and have relevant qualifications and experience. You can also ask for referrals from trusted friends, family, or colleagues. It is important to interview potential advisers and ask about their approach, fees, and conflicts of interest.
Conclusion
Choosing between an independent wealth adviser and a big bank advisor in Melbourne depends on your specific financial needs and goals. Independent advisers offer a broader, more objective perspective and holistic planning, which can be particularly valuable for professionals and business owners with complex financial situations. By understanding the structural differences, product availability, and fee structures, you can make an informed decision about the type of advice that is right for you. At Obsidian Wealth, we are committed to providing clear, objective, and holistic financial advice to help you achieve your long-term goals.