
7 Insurance Components a Single Adviser Should Coordinate With Your Investments
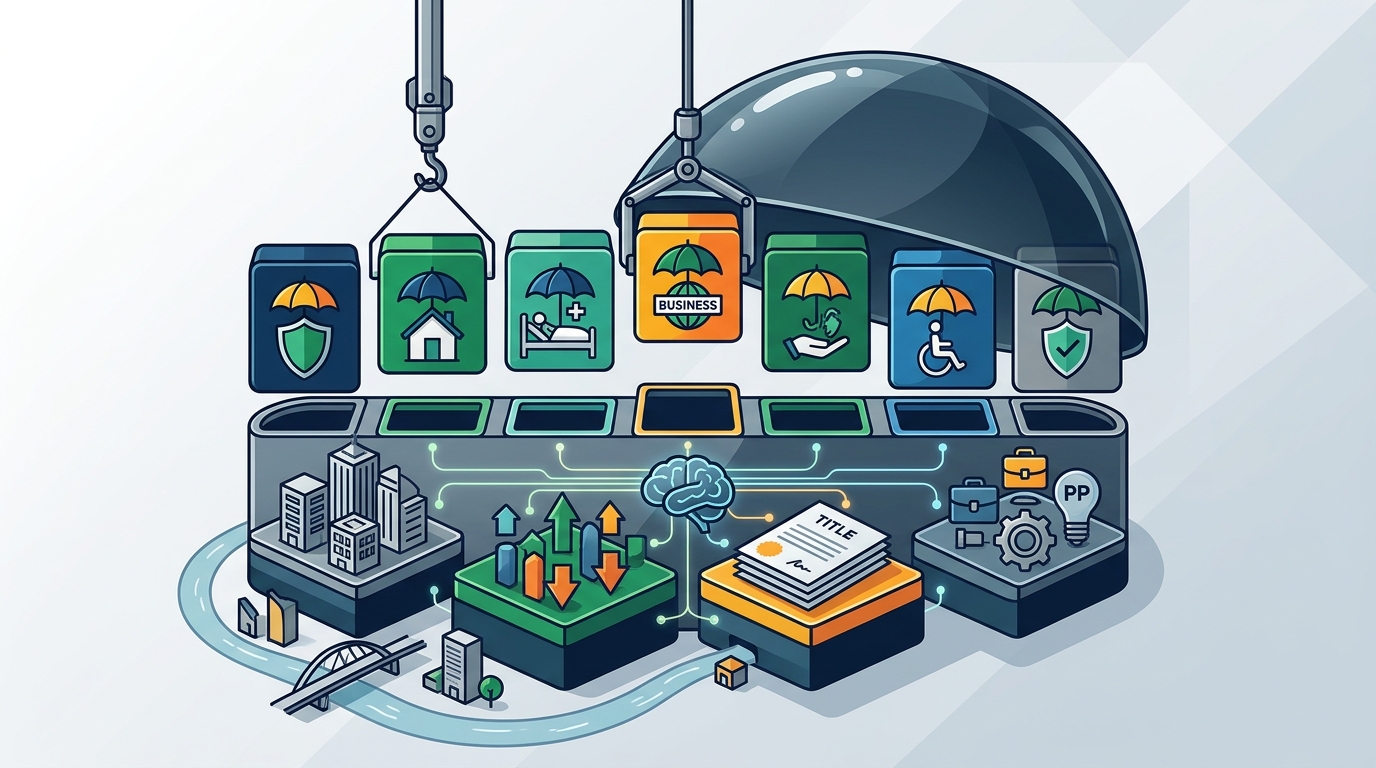
Insurance is often treated as a separate line item, but it is actually a structural layer that protects the investment strategy beneath it. When a single adviser coordinates your cover with your portfolio, they ensure that a life event does not force a sale of assets at the worst possible time. This integration is critical for high-income professionals and business owners in Melbourne who hold significant debt and complex asset structures.
1. Life Insurance Aligned to Debt and Asset Ownership
Your life cover must match the exact legal structure of your debts and assets. If your mortgage is held in a family trust but your life insurance is in your personal name, the payout may not be available to pay off the loan. A coordinated adviser ensures the beneficiary and the debt holder are legally aligned so the payout actually resolves the liability.
2. Total and Permanent Disability (TPD) Cover for Income Replacement
TPD cover protects your human capital, which is often your largest asset. For professionals whose income is high but not guaranteed, TPD provides a lump sum to replace future earnings. This prevents the need to draw down investment portfolios prematurely to cover living expenses during a long recovery period.
3. Income Protection for Cash Flow Stability
Income protection maintains the regular contributions that drive long-term wealth growth. If you cannot work, your salary stops, but your investment contributions should not. This cover ensures you can continue to fund your superannuation and investment accounts, keeping your compounding trajectory intact despite a temporary loss of income.
4. Trauma Cover for Major Medical Events
Trauma cover provides a lump sum for serious illness that does not necessarily stop you working. Conditions like cancer or heart disease can incur massive out-of-pocket costs and require lifestyle changes. This cover provides the capital to manage these costs without liquidating your investment portfolio or taking on high-interest debt.
5. Key Person Insurance for Business Owners
Key person insurance protects the business entity itself from the loss of a critical owner. For business owners, the business is often the primary asset. If a key person dies or becomes disabled, this cover provides funds to buy out their share or cover the loss of profit, ensuring the business remains stable and the personal wealth attached to it is preserved.
6. Business Succession and Ownership Protection
Ownership protection ensures a smooth transfer of business interests if an owner is incapacitated. This often involves cross-purchase agreements where insurance pays for the shares of the incapacitated partner. Coordinating this with your personal investment plan ensures that the business sale or transfer does not disrupt your broader retirement or wealth strategy.
7. Superannuation Death Benefit Nominations
Your superannuation death benefit must be nominated to align with your estate plan. Superannuation does not automatically pass to your estate; it goes to the nominated beneficiaries. A single adviser ensures these nominations are current and consistent with your will and trust structures, preventing legal disputes and tax inefficiencies.
Choosing the Right Coordination Approach
The best approach is one where your insurance, investments, and estate planning are reviewed as a single system. If changing one element requires a complete overhaul of the others, the plan is not properly integrated. Look for an adviser who views insurance as a risk management tool that supports your investment goals, rather than a standalone product.
Frequently Asked Questions
Why is it important for one adviser to handle both insurance and investments?
One adviser ensures that the risk management strategy supports the investment strategy. They can see how a life event would impact your portfolio and adjust the cover to prevent forced asset sales or tax inefficiencies.
Do I need both life insurance and TPD cover?
Yes, they serve different purposes. Life insurance pays out on death, while TPD pays out if you are permanently disabled. Both are necessary to protect your family and your future income stream.
How does insurance affect my investment portfolio?
Insurance prevents the need to liquidate investments during a crisis. It acts as a buffer that allows your portfolio to remain invested and continue compounding, even if your income is interrupted.
Can I manage my own insurance and investments separately?
You can, but you risk creating gaps or overlaps. Separate management often leads to inefficiencies where the insurance payout does not align with the legal structure of your assets or debts.
What is the role of an adviser in coordinating these components?
The adviser reviews your entire financial position, identifies risks, and structures the insurance to match your asset ownership and debt arrangements. They ensure all elements work together to protect your wealth.
Next Steps
At Obsidian Wealth, we integrate risk management with your investment strategy to ensure your wealth is protected from all angles. To discuss how your insurance aligns with your portfolio, book a call with our team.